For HIGH-EARNING COUPLES IN SINGAPORE:
If you're ever stuck deciding between an HDB, a resale condo or a new launch...
Know which property move makes sense for the life you want.
We start with your goals and finances, then compare your options,
so you understand what to buy, how much to commit and why.
Colin has advised over 300 investors and homeowners across Singapore.

You both earn well. So why is choosing your next home still so difficult?
With a good combined income, you have more options. But knowing what you can afford doesn't necessarily tell you which move is right for the two of you. These are some of the questions I hear from couples:
"Colin, we can afford it. But how much should we actually commit?"
The bank can tell you how much you can borrow. But that doesn't mean you should always borrow ALL that you can.
Sometimes, stretching for the right property makes sense. Sometimes, it doesn't.
The important thing is understanding what you're getting in return, and how that commitment affects your finances.
"We've done so much research. But which property should we actually buy?"
You've compared prices, rental yields, upcoming developments and market trends.
But just because a property looks good on paper doesn't mean it's the right purchase for you.
What matters is whether you're buying it at the right price, for the right reasons, and whether it fits into your overall plans.
"What if our plans change a few years after buying?"
Maybe you'll need a bigger home. Maybe one of you wants to take a career break. Or perhaps you'll want to invest in another property.
The home you buy today will affect the choices available to you tomorrow.
That's why it's important to think beyond getting the keys, and consider what you want your property to help you achieve next.
Two couples can afford the same home.
That doesn't mean both should buy it.
For one couple, stretching for a new launch might make perfect sense.
For another, buying resale or keeping their current home might be the better move.
The difference comes down to their financial position, what they're trying to achieve, and where they want to be in the years ahead.
What happens in the session
Every Agent Starts With the Property. I Start With You.
Here's exactly what we cover — and why the order matters.
Process — Your full position, mapped clearly
Your combined income, cash, CPF, existing property and financing position.
What you can put towards the move, and what you want to keep aside.
We start with your position before discussing a property.
Risk & Reward — What a good outcome looks like for you
.A home you enjoy. A stronger financial position. Room for a career change or a different family plan.
We weigh the potential upside against the commitments you would be taking on, and what happens if your income or plans change.
Product — Which move makes sense from here
Buying, upgrading, keeping what you own, or waiting.
We compare the choices against your position, rather than making your position fit a property.
And if I think you shouldn't buy it, I'll tell you.
The person behind the advisory
Meet Colin Ee
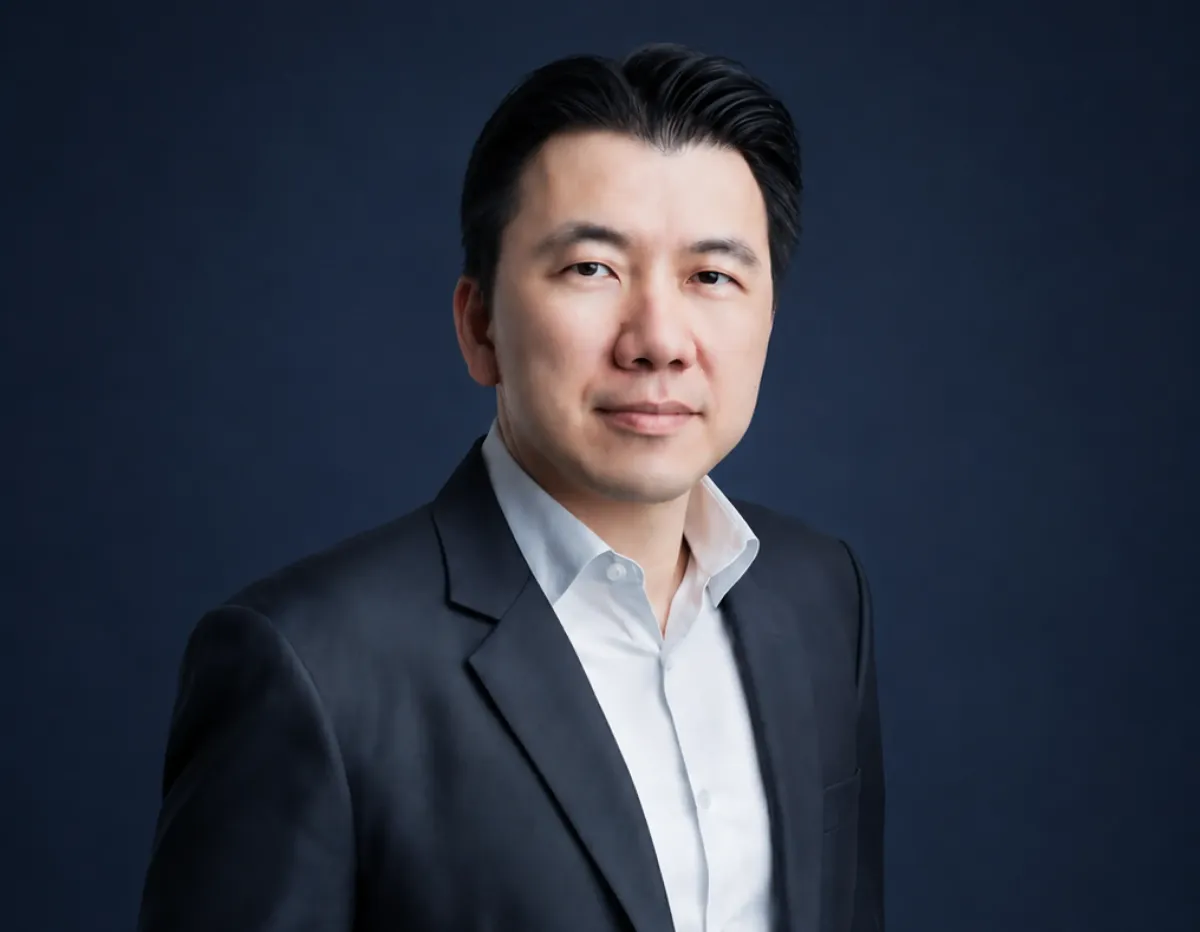
Colin started learning about property at 7. Not from school — but from watching his family lose their home in Serangoon Gardens when his father's business failed.
Over the next 20 years, they moved four more times. Each place smaller than the last.
That question — why does this keep happening — never left him. He went on to climb Mount Everest, was selected from 1,800 applicants into HSBC's Management Trainee Programme, and has spent 20+ years advising clients in Singapore on property structuring.
At HSBC, he learned that managing downside matters as much as chasing returns. On Everest, he learned that every decision at altitude is a risk management decision. That thinking is the foundation of his advisory practice today.
Every agent starts with the property. Colin starts with you — and that changes everything about what you end up buying.
Who this session is for
This session is for couples actively considering a property move and ready to look at their income, cash, CPF and current property position. You don’t need to have chosen a property.
A good combined income. A first purchase you want to get right.
You're weighing a resale HDB, a resale condo or a new launch.
You want to understand what each option leaves you with, not just whether the purchase is possible.
Two incomes. No kids. A chance to plan deliberately.
You’re deciding how to use your combined income to build a stronger financial future through property.
Whether you’re buying your first home or planning your next investment, you want to know which move is worth committing to.
An existing home. A next move that needs thinking through.
You're considering an upgrade, another property, or a change to what you already own.
Before you commit, you want to know whether it improves your position, not just increases your commitments.
Different Starting Points. Different Goals. Different Property Plans.
Here's how I've helped clients make property decisions based on their own financial position, rather than simply recommending the next property to buy.
John & Kim, Early 30s: Earning $20k+ Combined, But Unsure Where to Start
In 2019, John and Kim were newly married, and looking for their first home. Most agents they met encouraged them to skip the HDB and go straight for a condo or new launch.
But with so many projects and investment strategies being recommended, they still weren't sure where to begin.
The approach:
Started with their income, financial position and what they wanted to achieve.
Used my P.R.I.C.E. framework to evaluate their options before choosing a property.
Developed a clearer plan for their property journey, rather than chasing the next promising launch.
The outcome:
$1.6M → $5.2M in property portfolio value
From 2019 to 2026, their property portfolio grew from $1.6M to $5.2M in value.
Peter & Jess, Early 40s: Already Own Two Condos. What's Next?
Peter and Jess had a combined income of around $30k and no children.
They had already sold their HDB and bought one condo each. One to live in, the other to rent out.
But by 2022, they were stuck.
Buying another condo meant a hefty ABSD. Selling and buying again? Maybe. Keeping both and collecting rent? Also an option.
They knew the usual property strategies. They just didn't know which move made sense next.
The structure:
Reviewed their existing property portfolio and long-term goals.
Compared holding, selling and restructuring their existing properties.
Developed a portfolio strategy before evaluating suitable properties using my P.R.I.C.E. framework.
The Outcome:
$4.7M (2022) → $9.2M (2026) in property portfolio value
Rather than simply looking for another property to buy, we started by working out what their existing properties needed to achieve.
Raja, 45 — very careful, very aware of the age-loan ceiling
He knew the window to take on meaningful leverage was closing. Most advisors would have pushed him toward something aggressive. Colin worked within what he actually had.
The structure:
Sold HDB, got a strong price
Wife bought condo at $1.4M own stay — now $2.1M
He bought investment property at $1.2M — sold in 2025 for $1.5M, reinvested $1.6M into current property
The outcome:
~$1M in wealth built over 5 years.
No speculation. No stretch. Built entirely around what he actually has — not what sounded impressive.
Kelvin, 42 — single, 3-room HDB owner, earning $8,000/month
An agent came to him. New launch. 1-bedroom at $1.1M. "Upgrade lah. Private property. Better than HDB." It sounded like progress. It wasn't.
What the agent was selling:
Loan $825,000. Repayment ~$4,000/month — half his take-home
Smaller space. Harder to rent. Less financial flexibility
A property that locked him in, not one that opened options
What Colin structured instead:
Sold 3-room HDB. Bought 5-room HDB in a better location at $900K. Loan $450K. Repayment $2,000/month.
Both bedrooms rented at $2,000/month. Tenants cover his entire mortgage. Every month.
"A good upgrade gives you options. A bad upgrade quietly takes them away. The question is not whether you can afford it. It's whether the move actually improves your position." ~ Colin Ee
Patwant, 49 — "I want to retire. Not in 5 years. Now."
He was earning $4,000/month. He had an HDB worth $850,000. He was done working. Most advisors would have told him to wait.
The structure:
Sold HDB at $850,000 — restructured into two properties
Wife (age 40, earning $7,500/month)
Properties structured to generate rental income from 2015
The Outcome:
Drawing $2,500–$3,000/month in passive income since 2015.
He retired at 49. Still collecting over a decade later. The structure made it possible.
Let's work out what your next property move should be.
You've worked hard to earn well. Before you commit that income to a property, let's look at what the decision leaves you with.
Whether you're buying your first home, considering an upgrade or reviewing what you already own, we'll start with your position and compare the trade-offs.
Sometimes the next step is to buy. Sometimes it's to keep what you have. And sometimes it's not yet.
Let's figure it out together.
© 2026 Colin Ee. Singapore.